Until the other day, nothing surprised me when it came to the credit industry. Well, that all changed after reading an article in the Wall Street Journal about the Bank of America's newest credit card.
The article reads:
"The new Bank of America program is open to people who lack both a Social Security number and a credit history, as long as they have held a checking account with the bank for three months without an overdraft. Most adults in the U.S. who don't have a Social Security number are undocumented immigrants."
This has many thing wrong with it on so many levels. For the record, I am for giving anyone a chance in this country to become an American citizen and lay claim to the American dream. Further, I support a program that deals with the illegal immigrants in this country fairly providing them with the opportunity to become American citizens.
I had so many titles for this article.
"The New Payday Loan from Bank of America."
"The Crime Rewards Card from Bank of America."
If they are giving out credit when no credit report or social security card exists, then there is something in it for them. Just like every other player in the credit industry, they are depending upon human nature to take over. Human nature is to make mistakes when it comes to dealing with your money. As a result, the credit industry makes you pay dearly for it. Just try being one day late, and you will pay the maximum interest rate penalty forever.
It is difficult enough for English speaking Americans to understand the credit system. As far as illegal immigrants, I would imagine it is even tougher to understand. This is a system that is setting up good people to fail. As a result, the bank makes the money on higher rates and fees.
Is this really about helping an "underserved community" or about making money by in a sense issuing payday loans?
I was curious as to the terms and conditions on the account. In an attempt to find out, I called Bank of America. The first lady argued that they would never have a program that gave credit to someone without a social security card. The next lady said she knew what I was talking about and would send me to someone for more details. The next lady said the same and then cut me off.
I finally called a branch in Los Angelas where they are starting the pilot program. In her own words she said, "We don't have terms and conditions for this program. We set them up when we set the account up for each person." She couldn't tell me how high the rates would be or the fees and penalties.
However, she said that the bank was "trying to serve the underserved community." Bless her heart, she really believes that to be true. Of course, they have the perfect person there to set up these accounts. She said she understands the market because she is married to an immigrant.
This is just another aggressive scheme put together by a Bank that is more about excessive interest rates and penalties and the almighty bottom dollar.
Oh and did I mention..... They want to help out those who are breaking the law. The irony is that the common day criminal couldn't walk into the Bank of America and get a credit card. The common day criminal has a social security card that reports a crime. As a result of a crime reported on a credit file, their credit is shot with no options to getting a credit card.
However, if you are an illegal allien living in Las Angelas, it doesn't matter.
Friday, February 16, 2007
Thursday, February 01, 2007
Letter to Texas House Representative Charlie Geren
Dear Representative Geren,
I understand that you were denied an insurance policy due to the inaccuracy of your credit score. Due to a low credit score, the insurance company that you applied felt you were too much of a risk and as a result would not accept your application.
That actually surprises me. I thought that most politicians had a way around the system. Well, since you are experiencing the same problems of your voters and getting a taste of how the world works outside the capital, let’s take this opportunity to let this unfortunate mishap turn into a positive for all of us.
You might not be aware of some of the problems in the system of credit and credit scoring. As a State Representative you potentially yield a lot of power. Your colleagues in Washington have passed the buck to the states to pass the tough laws against the credit industry. This way they can still sit in the even more unrealistic world of career politician land and not have to do anything that disrupts their relationships with the credit industry who like to pay lots of money in campaign contributions. It is quite the cozy relationship.
Being a Republican you especially have a great opportunity to make a difference. Unfortunately, at least in Congress, it is the Republicans that love the political contributions from the credit industry. Unfortunately, they have lost power and now the Democrats (who have no love for the industry because the industry shows them no love) are actually starting to do something on a Federal level.
While that taste of reality is still fresh, take this opportunity to start a movement on the Texas state level that shuts down the anti-consumer practices of the credit industry. How about some new legislation that helps us out with unethical debt collectors? How about some help with usury laws on interest rates? How about some action on credit scoring?
You see in the real world consumers are struggling to get out of the debtors jail that politicians have helped build through the years.
You had mentioned that your score was low only because of inquiries of 4 major credit transactions. There is a low probability that those inquiries that you had during that time period would have done enough damage to lower your credit score to the levels were people are denied based on credit scores. Thus, you probably have many mistakes on your credit report that are bringing that score down. Of course, with better legislation, that also might not have ever happened.
Sincerely,
Bob Brooks


Thursday, January 18, 2007
How you Can Lower Your Credit-Card Rate
"How you can lower your Credit Card Rate" headlines the personal journal section of the Wall Street Journal. This article makes it sound easy. Just call the card company and tell them that you are going to move your transfer your balance and take your business elsewhere.
This was the meat of this headline article. Well, unfortunately, that is not the whole truth of the matter. Yes, if you have a good credit score, you have options. If your credit score is the 700's there is no reason why you should be paying anything higher than 6% on a balance transfer. The programs are out there. Of course, be careful of the 0% transfers. Those are filled with loopholes.
Yes, you should call them and tell them you are going elsewhere. They don't want your business to go because they know you can move it with ease.
Unfortuantely, it doesn't work that way with a lower credit score. They know that a consumer with a lower credit score does not have transfer options. Thus, there is no incentive to do the consumer a favor.
So, if you are in that unfortunate situation, here are a few tips:
1) Go ahead and call and make the request anyway- you never know someone might just lower it for you and you never have anything to lose.
2) If not, tell them you are committed to improving your credit score and your interest rates. Ask them what needs to happen to lower your interest rates. Some companies will lower your rates based on future good credit behavior. Time ends up being the real cure when it comes to high interest rates!
Above all, never attempt to negotiate the balance of the debt. The only thing negotiable with a credit account that is current is potentially the interest rate. If you ask about the balance, they will consider you a risk and you might end up in collections with a charge-off. I have known that to happen.
Tuesday, January 09, 2007
Finally Regulators are Going After the Equity Indexed Annuity Market
I have said for many years that the equity indexed annuities are one of the worst products for investors on the market. They represent the epitimy of irresponsible marketing. Below, is a note from the COO of Allianz Insurance Company. They have made billions of dollars selling these irresponsible products to unsuspecting investors.
They are pitched as the solution to all problems. You can make stock market returns without ever losing your principles. The agents have been getting rich selling them with commissions as that are paid out as high as 9%.
This is a long time coming and much needed in an industry that needs more regulation.
Remember, if is sounds to good to be true it is to good to be true.
From the COO of Allianz
I want to inform you about a developing situation that is generating significant media coverage about Allianz Life Insurance Company of North America. Earlier today, the Minnesota Attorney General's office filed a lawsuit against Allianz for alleged sales of unsuitable deferred annuities to senior citizens.
We strongly disagree with these allegations. I want you to know that we are confident that we have complied with Minnesota law and will vigorously defend this position. In her press conference, the Attorney General stated that her office had been in negotiations with us. However, we made repeated attempts over the past several weeks to meet with the Attorney General's office to provide additional information that could have prevented this action and our requests were flatly denied.
We are communicating to the media that our annuities are high-quality products that serve a range of consumer needs. More than 99 percent of our annuity policyowners have never filed a complaint with Allianz - a consumer standard of which all of us can be proud. We value all of our distribution relationships and we are committed to supporting you and will keep you updated on this situation as it evolves.
Doug ReynoldsCOO
Wednesday, January 03, 2007
$ 8,680,224,380,086.18 Reasons Why Debt Should be Number 1
Truecredit.com commissioned Roper Public Affairs & Media to gauge Americans’ thoughts about New Year’s resolutions. Four out of ten that were surveyed chose losing weight and eating better as the number one resolution for 2007.
Debt reduction came in second.
It gets even better. 48% of those surveyed say that losing ten pounds would be very or somewhat difficult for them in 2007, while 31% say paying off all their credit dcard debt would be difficult. (According to the Press Release)
Denial has taken on a new meaning. Although surveys are a small representation of the opinions and feelings of a large population, it is in many ways representative of the biggest problem in this country. This is a country in denial. As of December 29, total debt in this country amassed $ 8,680,224,380,086.18. Yes that is trillions of dollars.
There was one other little interesting tidbit of information. The jump in debt from December 28th until December 29th was the largest jump on record. (www.minyanville.com)
Since September 2000, the National total debt has jumped 53%. Of that total, personal debt in this country for the same time period jumped 43%.
It just seems like everyone is living in a fantasy world where financial decision making has no consequences.
Maybe the rationale is less time at McDonalds means more money saved to pay off debt and less calories consumed.
Friday, December 15, 2006
When $6.95 isn't so Free!
I love to listen to sattelite radio. It is a great way to get caught up on the news on the way to the office. It is also a great way to listen to Prudent Money (Sirius) every Saturday morning at 10 am central. (sorry for the plug)
However, I don't like listening to the commercials. It seems that most of these commercials that are aired on Fox and CNBC tell you the lastest way to get rich. This latest and greatest program will give you financial freedom. It is fast and it is easy.
"I made $ 5,000 a month just working part-time. It was easy."
"I applied these techniques for buying and selling real estate and in a few short months was financially independent."
Now these ads are enticing. You desparately want to believe that they are true. I would love to believe that someone was going to plant a money tree in my backyard. However, that is probably not going to happen.
You decide to go ahead and order the book and tape because you have nothing to lose. IT IS FREE!! This is the best part. They are going to give you this tape and book.
However, there is a small shipping and handling charge.
So, I decided to call a few of these life changing program call centers to hear the sales pitch. I called two different call centers. Both of these call centers for two different programs said exactly the same thing and in the same order. Keep in mind, that they were supposedly two different gurus who had written two different books.
Here was the best part of the conversation - What is the shipping and handling? She replies, it is a small charge of $ 6.95. So, let me get this straight. I am going to pay them $ 6.95 for the free items that are worth $ 50?
Here is the real deal -
1) There is no magic solution that is going to make anyone rich over night. If so, everyone would be doing it.
2) Nothing is free
Finally and most important..... This is a heck of a method to sell product. It probably costs a 3 or 4 dollars to make and ship the product. After all of their advertizing is covered, they are probably making a pretty nice little mark-up on that product that they are giving to you for free.
In addition, the free book and tape probably ( this is pure speculation on my part) give you the opportunity to actually buy something from them.
When you hear this sort of thing, just know it is nothing more than a marketing gimic designed to conveniently put dollars in their pocket.
Friday, December 01, 2006
When Sales are Down - Just Put Christ back into Christmas
"We, quite frankly, have learned a lesson from last year," Linda Blakley, a Wal-Mart spokeswoman, told USA Today. "We're not afraid to use the term 'Merry Christmas.' We'll use it early, and we'll use it often."
Bill O'Reilly - November 2005 - "I am 100% convinced...that the policy of not advertising, using the words, "Merry Christmas: will hurt the bottom line of these stores. It will hurt their sales."
Is it just me, or is it just to convenient to not have a backbone and do whatever possible to save Christmas retail sales this year?
Wal-Mart has had a teribble year. They have had a tough time hitting sales forecasts. In fact, these are some of the worst sales numbers in 6 years. Last year, they thought it was a great idea to be non-religious specific and instruct their employees to not say Merry Christmas.
To begin with, it was a stupid idea to take this action. Regardless of your religious beliefs, Christmas is a national holiday event. They were very passionate about going this route. Now all of the sudden when sales are declining, Christ makes it back into the stores?
I hope that the rest of America sees this for what it is worth. A company that has no moral backbone. I would have much more respect for Wal-Mart if they had stuck to their guns and their original beliefs back in 2005. Now, they do whatever they have to make sure that sales come through the doors at Christmas. It is a sad representation of what is happening in America.
Maybe next year if sales are better, they can just instruct their employees to say
Merry X-Mas
The Irresponsible Mortage Industry
A recent advertisement read:
“Are you Paying to Much for Your Mortgage?”
Then they show how you can pay $ 1,698 for a $ 510,000 mortgage.
Most consumers don’t understand how mortgages work. In today’s cash crunched economy, consumers are nlooking for ways to reduce their expenses. There are also those who are buying into the real estate boom and attempting to buy more house than they can afford.
Well, there is a industry that claims to solve all of those problems. It is the Loan Shark Mortgage Industry. Since people don’t understand the ins and outs of mortgages, they go to the “professional” to get advice on mortgages. In reality, they walk into the sharks den and get sold a horrible product that will only make things worse in the future.
These companies are marketing these irresponsible mortgages and taking advantage of people who are in hopes of buying a house when they can’t afford it or people who are in cash flow trouble.
There are some good people in the mortgage business. Alice White is someone that I confidentally recommend for anyone who is need of a mortgage. The problem is that people like Alice are far and few between.
Keep this mind when thinking about a mortgage.
You don’t pay too much for a mortgage unless your interest rate is higher than the current market for interest rates is paying. Don’t fall for the “pick a payment” scheme
Saturday, November 11, 2006
Be Careful the Headlines that you Trust
When reading anyone's opinions about finances, always have one question in the back of your mind. What is the agenda? For instance, here is an opinion made by an economist about the real estate market.
"The bad news is just about behind us. It appears that we have bottomed out."
That certainly is good news coming from the Chief Economist with the National Association of Realtors. I am sure that there is no agenda in that statement.
Let's consider another opinion about the United States Economy.
David Walker who is a comptroller has this to say about the United States Economy.
He describes the fiscal health of the economy as “a ship of state on a disastrous course that will flounder on the reefs of economic disaster if nothing is done to correct it.”
Credible? Agenda? Well, David Walker is the Comptroller General of the US Government. He is not an elected official. He has a secure 15 year term. He can speak the truth without reprucussions. He is one of the few Government officials who doesn't have to play politics. In fact he is going around the country warning people that we possibly are going to face a "financial tsunami."
He sees the real truth and he is the Chief Accountant/numbers cruncher for the US Government.
Now that we are out of the season of politics, make sure that you pay attention to the other side of the story. Beyond the agenda, there are some major problems that spell risk for your money.
Friday, November 03, 2006
Refinancing? Buying a New Home? The Big Banks want to be Your Friend
With the slump in real estate and increase in interest rates, the borrower/consumer now find themselves in the driver’s seat. Banks are seeing their revenues starting to slow and they want your business. So, they are willing to offer all types of incentives to gain your business.
Bank of America encourages you to apply with them and then go shop around. If you find a better deal, they will pay you $ 250.00 towards the closing costs of a loan with another company. Of course, it might take Congressional intervention to get that check. (Opps!! just thinking out loud and writing at the same time)
Charles Schwab said that they would give their current clientele a .25% discount on the rate for a new adjustable rate mortgage (awful choice) or home-equity loan. Amazingly enough they will give you a lower discount if you take out a fixed loan. Think through that with me. They will reward you more for taking out a loan that is not in your best interest and long-term better business for them and they will reward you less for taking out a loan that is much better for you.
Big banks (as I have stated many times) are not out to do you any favors. They are out to make money as fast as they can. This is evident through the way they take advantage of customers through credit cards and the bait and switch tactics used through many of their programs.
If you are buying a home or re-financing, go with someone that is not a marketing machine with dicey offers. Go with someone who can consult and be a trusted resource.
There are two ways to start. The smaller regional banks work hard at getting your business the right way. Many of the regional banks take the “hand shake” approach and treat banking customers the right way.
Go with a referral from a trusted resource. Alice White has been a frequent guest on my show. I have known her for over 25 years. Just last week she was able to save a Prudent Money reader almost a full percentage point off of what another broker was offering. She can be reached at alwhite@firsthorizon.com or 972-335-2252.
These are big decisions. Make sure that they are prudent decisions with a trusted resource. You don’t have time to over spend with another marketing ploy.
resources for this blog: www.minyanville.com and the Wall Street Journal
Wednesday, October 25, 2006
New Bible Version Takes Out All References to Money To Make A Point
“A new Bible translation is causing controversy after it cut out difficult parts surrounding economic justice, possessions and money. The new bible version, released by the Western Bible Foundation in the Netherlands, has created a storm by trying to make the Christian gospel more palatable. According to Chairman Mr. De Rijke the foundation has reacted to a growing wish of many churches to be market-oriented and more attractive. "Jesus was very inspiring for our inner health, but we don't need to take his naïve remarks about money seriously. He didn't study economics, obviously." According to De Rijke no serious Christian takes these texts literally.”
This is disturbing.
Let me dissect this one. Christ’s remarks on money were naïve? Christ didn’t study economics? Well Christ didn’t need to study economics and his points about money were very direct and on point. Yes, there are different interpretations based on the meanings of Greek versus how we interpret it today.
This is nothing more than making Christianity easier and watering down what it means to be a Christian. You can't pick and select what should or shouldn't be in the bible. Money is signficant.
Christ was very clear. You cannot have two Gods. You either worship money or God.
Putting money over God is in my opinion the biggest single problem that we have today as Christians. Money has its influence over almost every element of our life. It is easy to put money over God. This is why money is written about more than any other subject in the bible.
Take away the teachings of money and you take away one of the central messages of the bible.
How you manage your relationship with money determines how you manage your relationship with God.
Thursday, October 19, 2006
Tax Issues and a Trusted Source
I get many questions about tax situations through Ask Bob. I want to make sure that you aware of Dan Pilla. He considered the foremost expert on the IRS.
The Associated Press once said, “Dan Pilla knows more about the IRS than the Commissioner.” He has been on Prudent Money numerous times. For those listeners who are dealing with IRS issues, there are several resources.
First, there is Dan’s latest book The IRS Problem Solver. It is one of the most excellent resources that I have found on dealing with the IRS. It covers everything.
Second, Dan has an excellent web-site that is packed full of information along with a consultation service that is very reasonable.
Third, Dan is having a Taxpayer Defense Conference that might interest you.
WHAT WILL YOU LEARN?
1. How to Protect Yourself from Aggressive Audit and Collection Tactics.
2. How to Challenge Tax Audits
3. How to Stop Wage Levies and Bank Levies, and Lift Tax Liens
4. How to Negotiate Reasonable Payment Terms with the IRS.
5. How to use the U.S. Tax Court to Your
6. How to deal with Delinquent Tax Problems.
7. How to Avoid Audits and Enforcement actions.
As a registered attendee, you can receive - at no additional cost - a personal, private consultation with Dan or a member of his private network of attorneys or and accountants who specialize in IRS issues. You will walk away with specific answers to your specific IRS questions and problems. Often, this consultation is all you need to solve your problem.
Monday, October 16, 2006
Goldilocks or the 3 Bears - Major Crossroad for the Markets
There are two theories concerning the future of the economy. One theory could have a devastating impact on the stock market and the other would potentially just be a minor event.
Regardless of your opinion, the majority opinion is that the economy is slowing down. The question is how slow will it go?
There is the soft landing theory. This means that the economy is going to slow down just perfectly without any problems. This is the Goldilocks economy.
Then there is the hard landing. This means that things didn’t go so well and we end up in a recession. This would be the 3 Bears scenarios.
The Goldilocks economy is not much of a threat to the stock market. The hard landing scenario indicates a decline on the average of 30% or more in stocks creating a mean bear market. That is based on historical data.
You definitely want to be standing on the right side of the fence on this one. Keep in mind that out of the last 16 economic slowdowns, only 1 (1994) ended up being a soft landing. I would imagine that the majority were predicted to be the best case scenario. That seems to be status quo for most economists.
Today the question of Goldilocks and the 3 bears is extremely important. The stock market (as represented by the S&P 500) is at a major point. There is a good probability that this ends up being a major stopping point for the 4 year bull market. It is important to watch what the stock market does at this level. Depending on where this market heads over the next 3 to 4 months, it could be a predictor of either the Goldilocks or 3 Bears scenario.
The stock market is a great indicator of the future. Thus if the 3 bears scenario is in our future it should be reflected in the stock market before a recession occurs with a mean bear market. If the stock market continues to act well, then it would be potentially predicting a soft landing for the economy. This would indicate a continuation of a bull market that started back in October 2002.
The moral of the story is - Be Careful How you Eat Your Porage!
Wednesday, October 11, 2006
I Pity The Fool and other Scientific Indicators
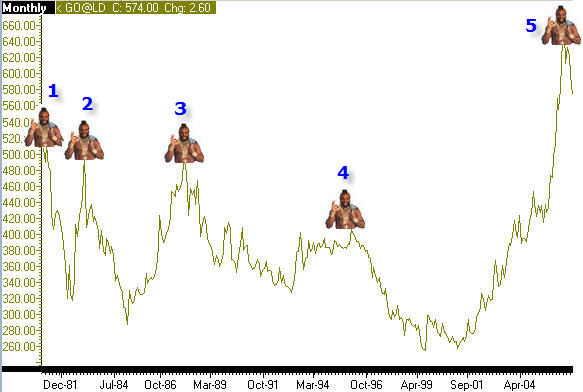
I felt compelled to bring you an excerpt from a site that I follow throughout the day http://www.minyanville.com/. I have spoken about the scientific approaches to managing money. This is one of the big time indicators that you can use for the Gold market. Of course, I am just kidding.
This is pretty funny stuff. Mr. T debuted with his reality tv show last night. As one might expect, it didn’t go over very well. It appears that Mr. T and his Gold Chains have some influence over the Gold markets every time he hits milestones in his career.
I bring you the Mr. T Gold Indicator Key
1. 1981 - With gold at all-time high, Mr. T lands role in Major Blockbuster, Rocky III.
2. 1982 - Gold rebounds from sharp sell-off, but peaks as Mr. T lands role in hit TV series The A-Team.
3. 1987 - The A-Team is canceled, its final episode airing in March 1987... a final farewell for Mr. T?
4. 1996 - Mr. T returns to star in comedy cult classic "Spy Hard," as "Helicopter Pilot."
5. 2006 - Mr. T returns to television as star of reality show "I Pity the Fool." Series roundly panned by critics suggesting appetite for society's symbols of gold has peaked.
Monday, October 02, 2006
A Bubble is a Matter of Perception or a Matter of Reality
A Bubble is a matter of perception writes one writer regarding real estate. She claims that real estate is not in a bubble because prices on real estate cannot go down 50% over night.
She writes, “A bubble is a market in which the value of the key asset is inflated based on speculation and psychology. Because of this, true bubble markets can burst overnight when something happens to shatter the perception of value.”
The first part of her sentence describes the residential real estate market. The price of residential real estate became initially inflated because of two reasons. First, the barriers to entry were removed. The mortgage industry made it to where just about anyone could get a mortgage whether they truly qualified or not. Interest rates were falling to historic lows. This increased buying activity.
Second, as a result of the first reason, investors started jumping on the increase in activity and spurred the speculation by flipping houses and properties.
Increased buying increases the prices of the real estate. Thus it was created through cheap money (low interest rates) and easy to get mortgages with choices of payment.
True bubbles can burst overnight. However, it took 25 months for the stock market to deflate from its bubble. That didn’t happen overnight and that was a bubble.
She calls it a corrective cycle. Thus indicating that this is just going to go through normal times and then real estate will start going back up. There is a big difference between this time period and other cycles.
In the past, we weren’t dealing with the irresponsible lending and borrowing that has taken place. Over 2 trillion dollars worth of adjustable rate mortgages will be coming due over the next two years. Just the small amounts of ARM’s that have come due recently, have dramatically increased the foreclosure rate. As this happens, real estate prices should continue to be under pressure. In addition, rising interest rates have also dampened real estate buying.
Buyers typically don’t buy while prices are falling. They wait for a better deal. They also buy much less in rising interest rate environments. Finally, people that walk away from mortgages because of rising interest rates and the inability to pay force pressure on markets. Thus, real estate could fall a lot lower before it starts recovering making it look like a bubble rather than the perception of one.
Friday, September 29, 2006
Reducing Clutter by Ashley Hodge
I am on a quest to reduce stuff. My wife would attest that one of my favorite things to do is to take a trunkload of possessions to the Salvation Army or Goodwill. There is nothing more satisfying to me than to find a different home for possessions that we do not use regularly. This is a problem with most American families I know. We have way too much stuff. Books like Affluenza and Organizing From the Inside Out address this issue. I wrote a chapter on our need to simplify in my own book- Stewardship Mandate.
Being organized and simplifying is a battle that must be fought daily. Clutter like weeds in our yards takes on a life of its own if we are not vigilant to root it out. read more
Being organized and simplifying is a battle that must be fought daily. Clutter like weeds in our yards takes on a life of its own if we are not vigilant to root it out. read more
Thursday, September 28, 2006
Headlines - It makes you wonder?
Why didn’t Bank of America get more than just a hand slap for not detecting money laundering for terrorists?
Is there more to the story?
I wonder how much in banking fees Bank of America made while all of their “detection” systems apparantly “didn’t work?”
October 2003
Bank of America, SAS to Battle Money Laundering
The International Monetary Fund estimates that between $800 billion and $2 trillion is laundered each year worldwide. Bank of America, currently the third-largest bank in the United States by assets and the nation's largest consumer bank, has selected SAS, the leader in business intelligence, to power its anti-money laundering program.
Bank of America, a SAS customer for 25 years, said it would use SAS to address requirements of the USA PATRIOT Act, passed by Congress after the attacks of September 11, 2001. The Act requires financial institutions with accounts in the United States to establish "due diligence" policies and procedures to prevent, detect and report possible instances of money laundering or terrorist financing.
Bank of America said it then uses predictive models from SAS to understand and examine potentially suspicious patterns or anomalies in financial transactions. The ability to monitor unusual or suspect behavior is essential for its anti-money laundering effort, according to Bank of America.
In addition to analyzing suspect behavior to detect and prevent money laundering and terrorist financing, the bank will monitor and analyze broker behavior, reporting risky situations, to help protect customer and company interests.
September 2006
Bank of America settles money laundering probe
NEW YORK (Reuters) - Bank of America Corp. (NYSE:BAC - news), the No. 2 U.S. bank, has agreed after a multiyear investigation to pay $7.5 million to settle charges it failed to prevent money laundering, the Manhattan District Attorney's office said on Wednesday.
Bank of America failed to detect that Brazilian companies were using a money transfer business' bank account to launder money, Manhattan District Attorney Robert Morgenthau said in a statement.
Money transferers transmitted an estimated $230 billion of funds in 2005 globally, but regulators and prosecutors have been trying to clamp down on the business to prevent money laundering and choke off funding for terror organizations.
Monday, September 25, 2006
Only You can be Responsible for your Identity
I am hearing of more and more instances where companies and governmental agencies have had personal information for individuals stolen. Identity thieves are very smart individuals. At the rate that this information is missing, they are apparently getting smarter.
Following an internal audit of the U.S. Census Bureau, the following was discovered:
217 laptops
46 portable data storage devices
15 handheld devices
All of the above was discovered to be stolen or missing from inventory. They audit shows that this started back in 2003.
You would think an agency associated with the Government would be even more protective.
What can you do about it?
The simple solution is to have your credit monitored. The first place the majority of identity thefts occur is with a simple credit check. If there is anything out of the ordinary happening with your credit report, you would be notified.
I have many ask who I trust. I only trust www.Truecredit.com. Although I have appeared in their national advertising campaign, I receive no monetary compensation for promoting their business. In fact, we have arranged to pass on any promotional fees that we would receive to Prudent Money listeners.
If you go to this link, you can get $ 5 off their 3 in 1 credit report package. They have some great packages. The most important is the credit monitoring for all 3 agencies. I think that everyone should have this service. They also have a package where you get the credit monitoring along with unlimited views of your credit reports. I cannot think of a better combination!
Credit monitoring along with being pro-active with your credit reports represents the first line of defense to Identity Theft!
Tuesday, September 19, 2006
Stewardship Plan - Money by Ashley Hodge
(this is another great post by Ashley Hodge on stewardship)
It is amazing what God teaches us in short periods of time. Seven years ago my attitudes towards money were selfish and not biblical. I was introduced to a Crown Financial Ministries Bible study and those beliefs began to change.After reading many books on the subject of the stewardship of money, I began to write down a philosophy of money that hopefully is in line with God's revealed will.
I published a book-Stewardship Mandate- in June of 2005 where I summarized those beliefs along with ideas about the stewardship of abilities, time and health as well.I am currently working on a edit of Stewardship Mandate and I am amazed at how God is revealing new things to me all the time. Although I stand behind 95% of the things I originally wrote, I often cringe and think, "I didn't communicate that very well," or "Why did I write that?"
Read more.....
Prudent Resources
From time to time, I want to use this forum to give you some of the links that I am reading. Todd Harrison who has been on my show in the past, has an excellent article on CBS Marketwatch entitled Why Falling Oil May note be Great News.
Then there is my weekly favorite writer John Mauldin. John has been on the show several times and writes some of the best insight each week. It is amazing that he doesn't charge for this newsletter. John Mauldin's Frontline Thoughts.
I always want to keep you posted on good information. Keep checking back to the blog.
Education and being informed is the key to effective stewardship. This is just another good stewardship practice.
Keep the Faith
Bob
Subscribe to:
Posts (Atom)


